


Specialty Fertilizer Manufacturing
A Market Shift That Every Agri-Entrepreneur Must Know
The move is the biggest structural change in the fertilizer industry in decades in India and has been closely followed by Economic Times. Huge investments in the bulk commodities such as urea and DAP are no longer being made by major fertilizer companies in India, according to a recent report in Economic Times. Rather, they are actively shifting their focus toward specialty products such as chelated micronutrients, water-soluble fertilizers, nan fertilizers and controlled release products. This isn’t a minor tweak to the product. This is a complete strategic reorientation, resulting from the pressure on the margins, the reform of subsidies and a new farming demand cycle.
Reuters reports in the Economic Times that the fertiliser majors are putting money behind specialty products as a clear sign of the times of bulk fertilizers are coming to an end. The full report on the Economic Times can be read here, Fertiliser Giants Bet Big on Specialty Products – Economic Times
What implications does this have for Indian entrepreneurs and MSMEs? It translates to a huge vacuum in the specialty fertilizer production sector. While large players are going upscale, they can’t cater to every geography, crop type and size of a farm. This is the perfect window for small, agile manufacturing startups to fill — today.
Get Detailed Insights from This Book: Complete Biofertilizer and Organic Farming Technology Book
The specialty fertilizer market is also expected to grow at a rapid pace, with water-soluble fertilizers alone accounting for USD 17.9 billion of the global market in 2025, growing at 6.5% annually. The country imports more than 90% of the essential water-soluble inputs. Recently an indigenous WSF technology has been developed by a start-up company in Nagpur which is commercially viable and backed by the government. For entrepreneurs, the opportunity to enter into this sector is the best one in years.
What Recent Economic Times Reporting Means
The specialty fertilizer pivot has definitely been the business strategy of the list’s top agrochemical firms, according to the Economic Times. So, let’s dissect what this ET highlighted development means.
The Core Development
Deepak Fertilisers, the country’s biggest technical ammonium nitrate producer, have already started moving from commodity to specialty chemicals. It launched specialty pivot with introduction of pharma-grade IPA and solar-grade nitric acid. Deepak’s water-soluble fertilizer volumes grew by 73% YOY, as per market analysts quoted by ET. The same strategy is being played by other major players like Coromandel International, GSFC and RCF.
The Market Signal
Once the biggest fertilizer companies start investing in specialty products, it is clear to the founders and MSMEs. High margin specialty formulations attract large companies with long-established distribution networks, strong brand recognition, and regulatory approval. This indicates much better unit economics for specialty products — and that market demand has become sufficiently large to justify the premium for precision nutrition.
Founder and MSME Implications
Large fertilizer producers tend to scale and standardise their operations. They are not able to provide an efficient service to micro-markets, which are some crops or local soil deficiencies, or custom nutrient blends for small farms. This makes opportunities for small scale manufacturing plants to make specialty fertilizers suited to particular geographic regions and crops very real and expanding. Grape growers in Maharashtra, potato growers in Punjab and bananas growers in Andhra have different micronutrient requirements. These needs can be better served by a specialized manufacturer, rather than a national conglomerate.
Startup Opportunity Signal
The Economic Times development bears out: India’s specialty fertilizer business is about to take the dive into hyper-growth. Businesses that make the investment to get manufacturing going within the next 12 to 24 months will reap rewards of first-mover benefits, developing relationships with progressive farmers as their first distributors, and brand recognition. It is an area where products with quality certification and scientifically developed, available at 3 to 5 times the margin of conventional fertilizers.
View Full Project Details: Fertilizer Manufacturing Projects
Why the Specialty Fertilizer Industry Is Growing in India
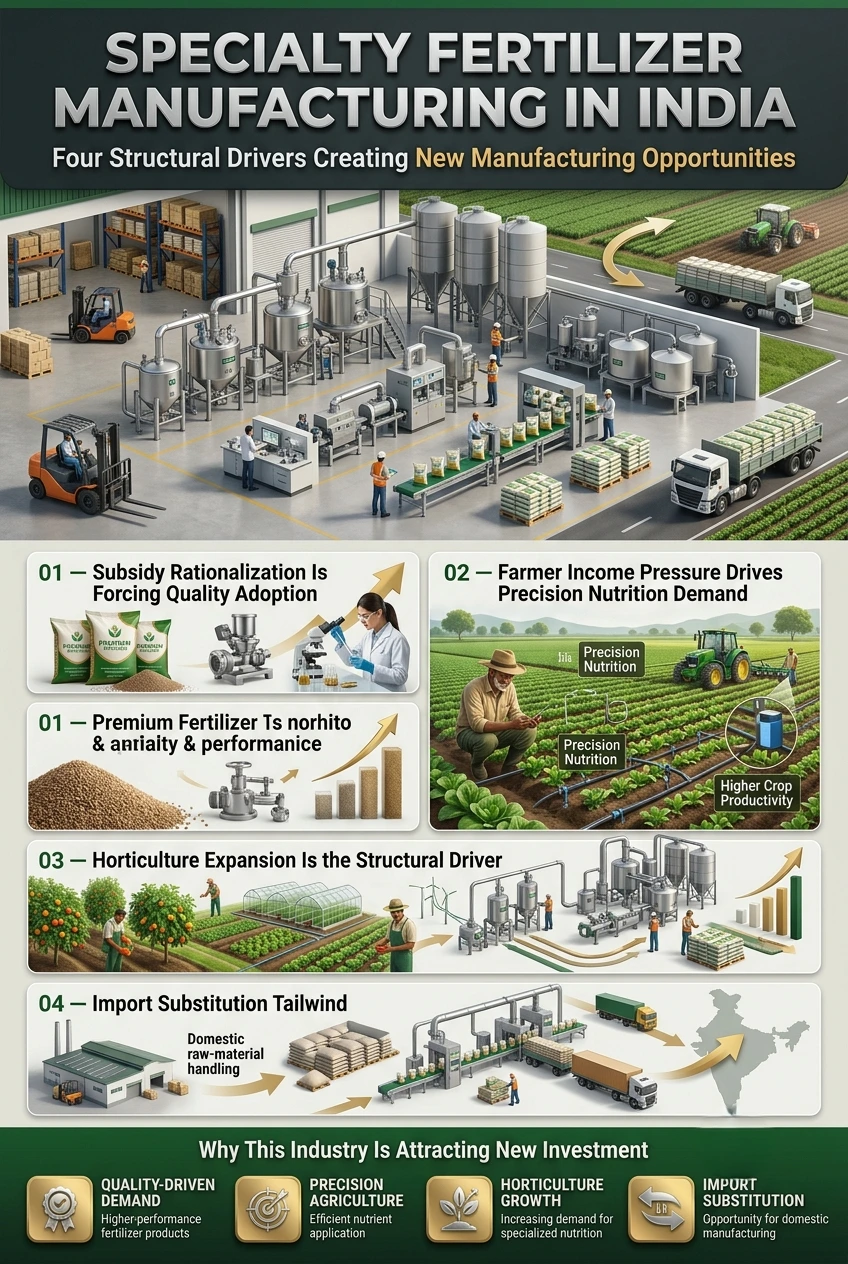
India’s specialty fertilizer growth story is being fuelled by several forces, and understanding them enables founders to get the size right.
1. Subsidy Rationalization Is Forcing Quality Adoption
The subsidy bill for fertilizers has surpassed the ₹1.75 lakh crore mark in India for FY2024. The government has been steadily progressing towards the Nutrient Based Subsidy (NBS) framework, which aims to advocate efficiency instead of volume. This policy change is very detrimental to the manufacturer of poor-quality bulk fertilizers while favouring companies that can show a crop benefit. The application of specialty fertilizers — where nutrients are more efficiently taken up — is the ideal fit with the goals of NBS.
2. Farmer Income Pressure Drives Precision Nutrition Demand
India’s farmers are stuck in a bitter dilemma of increasing input prices and declining prices for commodities. The only way to get out of this mess is to improve the yield — and specialty fertilizers can provide that. Yields typically increase by 25–40% on farms where farmers use drip irrigation and water-soluble NPK fertilizers. Precision nutrition adds ₹1.5 lakh to farmer’s income through investments of ₹80,000 per acre on tomato and grape crops. This ROI leads to authentic demand for higher quality specialty products.
3. Horticulture Expansion Is the Structural Driver
Horticulture (fruits & vegetables, flower spice crops) now contributes more to the economy than field crops in India. According to the National Horticulture Board, India yields more than 350 million tonnes of horticulture crops every year. Specialty fertilizer inputs are much more effective for horticulture crops than for field crops. Demand for specialty fertilizer increases in proportion to the total increase in farming output of high-value horticultural crops as farmers switch from wheat and rice to specialty crops as a result of PM-KISAN linkages and APEDA export incentives.
4. Import Substitution Tailwind
In FY2023-24, India purchased 3.5 lakh tonnes worth of ₹2,000 crore water soluble fertilizers, of which almost 90% came from China and Israel. Geopolitical uncertainties, supply chain volatility and currency devaluation are making it less and less feasible to rely on imports. The government has put emphasis on the production of domestic WSF in line with Make in India initiative. This is a once-in-a-lifetime confluence of domestic demand pull and government policy push that all favor new players in manufacturing.
The Economic Times has been monitoring this import substitution trend in the agrochemical industry in India all along. Read the Economic Times – fertiliser industry coverage for the complete ET coverage of the specialty fertilizer transition.
Government Policies and Incentives for Specialty Fertilizer Manufacturers
The Indian government has an in-depth policy framework conducive to specialty fertilizer production. The entrepreneurs who choose to make this move are not beginning fresh, but rather they are tapping into a network of financial assistance, regulatory support and market access programs.
Pradhan Mantri Formalisation of Micro Food Processing Enterprises (PM-FME)
Although its focus is on food processing, PM-FME’s framework can support capital subsidies and capacity building for agri-value-chain manufacturing plants, such as fertilizer blending units.
MSME Technology Upgradation Schemes
The Ministry of MSME provides a credit linked capital subsidy scheme (CLCSS) of up to 15% capital subsidy for the technology upgradation of MSMEs, directly applicable to specialty fertilizer equipment. Details at: www.msme.gov.in
Startup India Recognition and Tax Benefits
Department for Promotion of Industry and Internal Trade (DPIIT) Support
Within import substitution policy, DPIIT has focused on specialty agrochemicals (AGROCHEM) production. Through: dpiit.gov.in, industrial licensing, investment facilitation and policy advocacy for manufacturers are available.
Make in India — Agriculture Inputs Category
The Make in India initiative specifically includes fertilizer as a focus sector and provides support for the technology adoption, export market engagement, and facilitation of investors. Visit: www.makeinindia.com
SIDBI Financing for Agri-Manufacturing
SIDBI offers a dedicated credit product for agri-input manufacturers such as term loans for greenfield specialty fertilizer plants at concessional rates. Explore at: www.sidbi.in
Fertilizer Control Order (FCO) — The Regulatory Framework
Every manufacturer of special fertilizers has to be registered under the Fertilizer Control Order – 1985 (amended). In India, the sale of any fertilizer requires FCO registration. This includes State Agriculture Department approval, product testing at recognized laboratories and renewal annually. Early compliance with FCO gives manufacturers a regulatory moat to chase away the smaller players.
State-Level Incentives
Many states have other incentives for specialty fertilizer production:
- Capital subsidy 25% for agri-input manufacturing units in drought prone districts under Mahaagri scheme in Maharashtra.
- Electricity tariff subsidy and land at concessional rates for agri-sector units, Industrial investment promotion policy, Rajasthan.
- AP: Agriculture Department direct procurement partnerships for specialty fertilizer units in the state’s Horticulture belt.
- Gujarat: Development of chemical and fertilizer cluster at Dahej and Ankleshwar industrial zones under Chemical and Fertiliser Cluster Policy.
6 Manufacturing Business Ideas for Specialty Fertilizer Startups
As per reports in the Economic Times, the Indian fertiliser giants are shifting gears from the traditional market, manufacturing opportunities arise straight out of the market shift report. These ideas are opportunities for a particular gap which large-scale manufacturers cannot be able to fill in efficiently.
1. Water-Soluble NPK Fertilizer Manufacturing Plant
Fastest growing segment of the specialty fertilizer market in India is water soluble fertilizers (WSFs). The fully soluble NPK formulations (19:19:19, 20:20:20, 13:40:13) are drip irrigated and fertigated. India bought ₹2,000 crore worth of WSFs in FY2024, 90% of which came from China. Domestic manufacturing unit can produce WSFs around 15–20% lesser cost compared to imports and also supply response time is faster.
- This is a capital-intensive investment ranging from ₹50 lakh to ₹2 crore based on the capacity, 1MT/day to 10MT/day.
- Maintenance: Maintenance of key equipment in accordance with the manufacturer’s requirements.
- Target Market: Drip irrigated horticulture farms, contract farming aggregators, cooperatives
- The profit margin is 22–35% on finished product compared to 6–8% on bulk urea.
- Mandatory — Product registration by State Agriculture Dept. is required.
Related Article: How to Start a Gel-NPK Fertilizer Manufacturing Business in India
2. Nano Fertilizer Manufacturing Unit
With commercial success of Nano Urea, IFFCO has proved the feasibility of nano fertilizer category in the industrial level. A technology pathway and regulatory framework has now been proven by private manufacturers. Nano fertilizers provide nutrients at molecular level that helps in reducing the nutrient use by 50% while improving the crop response by 20-35%. The government is actively encouraging use of nano fertilizers as a substitute of imports and reduction in subsidy.
- Investment Amount: ₹1.5 cr – ₹5 cr (Capital Intensive, High Margin)
- Key Equipment: High shear nano emulsification systems, particle sizing analyzers
- Product Types: Nano Urea, Nano Zinc, Nano Copper for rice, wheat and horticulture.
- Regulatory Path: Registration with FCO + DPIIT recognition of startups + Funding from DST S&T PRISM
- Strong demand for nano agri-inputs in Bangladesh, Sri Lanka, Nepal.
3. Chelated Micronutrient Fertilizer Manufacturing
Micronutrient deficiency in soil is a crisis in Indian agriculture with more than 48% of Indian soils being zinc deficient, Iron, Boron and manganese deficiencies are widespread in the major horticulture belts. Chelated micronutrients (EDTA-chelated zinc, iron, manganese, and copper) provide bioavailable forms that plants absorb 3–5 times more efficiently than conventional sulfate forms. The product offers technical differentiation, while domestic competition remains limited.
- Investment Details: ₹75 lakh – ₹3 crore is the investment requirement.
- The key inputs are metal salts such as zinc sulfate, ferrous sulfate, chelating agents such as EDTA and DTPA.
- Price: Grape, pomegranate, banana and vegetable growing states, Maharashtra, AP and Karnataka
- This is the highest margin in the specialty fertilizer category, at 30–45%.
- Copycat Competition is Limited by Technical Complexity

4. Humic Acid and Fulvic Acid Fertilizer Manufacturing
Humic substances (humic acid, fulvic acid, potassium humate) are soil conditioners which can significantly enhance the efficiency of nutrient uptake, water holding capacity, and soil microbial health. The two major raw materials for humic acid production are leonardite which is available in large quantities in Rajasthan and Madhya Pradesh in India. Domestic production of humic acid concentrates is highly cost competitive against imports.
- Investment: ₹40 lakh to ₹1.5 crore (for raw material-oriented business)
- Key Process: Alkaline extraction of leonardite + acidification + spray drying
- The substances and products manufactured are potassium humate powder (70%+ humic acid) and liquid humic concentrates.
- Organic farming transition farmers (OPF), horticulture growers and tea and coffee estates (TC)
- EU demand for organic soil amendments is increasing at an annual rate of 12%
5. Slow-Release and Controlled-Release Fertilizer (CRF) Manufacturing
- Investment Required: ₹2 crore – ₹8 crore (polymer coating equipment is capital-intensive)
- Key Equipment: Rotary drum coaters, polymer application systems, curing ovens
- Target Segments: Golf courses, landscaping, sugarcane cultivation, nursery production
- Margin Profile: 35–50% gross margin — premium product with limited domestic supply
- Technology Access: IARI and NBSS&LUP have publicly available CRF technology for licensing
6. Bio-Stimulant and Seaweed Extract Fertilizer Manufacturing
Bio-stimulants — seaweed extracts, amino acid formulations, plant growth-promoting rhizobacteria (PGPR) — are the fastest-growing specialty agri-input category globally. India has 7,516 km of coastline with abundant seaweed biomass, particularly along the Gujarat and Tamil Nadu coasts. Processing coastal seaweed into concentrated liquid bio-stimulants creates a raw material-advantaged, export-oriented manufacturing business.
- Investment Required: ₹60 lakh – ₹2.5 crore
- Key Process: Seaweed collection → cold water extraction → concentration → packaging
- Certifications: OMRI certification for organic market access; EU organic standards for export
- Export Markets: EU, US, and Australia — paying USD 8–15 per litre for certified bio-stimulants
- Anchor Customers: Organically certified farm clusters, export-oriented horticulture farms
Import–Export Opportunity Analysis
The specialty fertilizer sector offers India a rare dual opportunity: aggressive import substitution domestically, and a growing export market internationally. Both create manufacturing incentives simultaneously.
Import Substitution Opportunity
India’s current import dependence in specialty fertilizers is extraordinary. Over ₹5,000 crore worth of specialty agri-inputs — WSFs, micronutrients, bio-stimulants, amino acids — are imported annually. With China as the primary supplier, geopolitical risks are high and supply chain reliability is questionable. Every domestic manufacturing unit that achieves quality certification directly displaces an import dollar.
Export Markets for Indian Specialty Fertilizer Manufacturers
- Bangladesh, Nepal, Sri Lanka: Rapidly growing horticulture sectors with import demand for WSFs and micronutrients.
- Africa (Kenya, Ethiopia, Tanzania): Donor-funded precision agriculture programs creating specialty fertilizer import demand.
- ASEAN (Vietnam, Indonesia, Philippines): High-value crop expansion driving WSF adoption.
- European Union: Growing demand for organic bio-stimulants and seaweed extracts under farm-to-fork sustainability mandates.
DGFT Export Schemes for Specialty Fertilizer Manufacturers
The Directorate General of Foreign Trade provides Remission of Duties and Taxes on Exported Products (RoDTEP) benefits and Duty Drawback schemes applicable to specialty fertilizer exports. Manufacturers should register at: www.dgft.gov.in
APEDA Export Facilitation
The Agricultural and Processed Food Products Export Development Authority supports agri-input exporters — including specialty fertilizer manufacturers — through market intelligence, buyer-seller meets, and trade fair participation. APEDA-registered manufacturers gain access to international buyer databases and export promotion subsidies.
Find the most profitable startup for your investment range
Indian MSME Success Stories in Specialty Fertilizer Manufacturing
Katyayani Organics — Pune, Maharashtra
Katyayani Organics began as a small agri-input formulation startup in Pune and grew to become one of India’s recognized specialty fertilizer brands. The company built its market by focusing on scientifically formulated crop-specific products — separate NPK grades for tomatoes, grapes, and banana. Their direct farmer engagement model and technically trained sales force allowed premium pricing in a market accustomed to commodity inputs.
Nagpur WSF Technology Startup (S&T PRISM)
A Nagpur-based research and development company recently achieved a significant breakthrough by developing indigenous water-soluble fertilizer manufacturing technology. The startup, supported by the Department of Science & Technology under the S&T PRISM scheme and the Ministry of Mines, developed formulations using locally available minerals. Their technology has already demonstrated 35% water savings in banana farming and profit gains of ₹98,000 per hectare. This validates that technology-driven MSME startups can compete directly with established importers.
ICL India Expansion — The Foreign Investor Signal
Global specialty fertilizer leader ICL Group established a new manufacturing facility in India spanning 7 acres to produce water-soluble fertilizers tailored for local soil conditions. When a global agrochemical major invests in domestic manufacturing to serve Indian farmers, it validates the market size and confirms that local manufacturing economics are viable. Indian MSMEs entering now have the advantage of lower overheads and deeper farmer relationships.
About NPCS — Niir Project Consultancy Services
Planning to enter the specialty fertilizer manufacturing space? NPCS — Niir Project Consultancy Services — is India’s most trusted name in industrial feasibility research, plant and machinery sourcing guidance, and business startup advisory for manufacturing entrepreneurs.
NPCS has published detailed feasibility reports covering water-soluble fertilizer manufacturing, chelated micronutrient production, bio-stimulant processing, and specialty NPK blending plants. Each report covers raw material sourcing, plant layout, equipment specifications, financial projections, regulatory compliance, and market strategy — everything a founder needs to make an informed investment decision.
With over 5,000 feasibility reports delivered and clients across 50+ countries, NPCS brings practical industrial intelligence that no generic business plan can replicate. Whether you are investing ₹50 lakh or ₹10 crore in a specialty fertilizer plant, NPCS provides the research backbone that separates successful manufacturers from those who learn expensive lessons in the field.
Data Table: Specialty Fertilizer Manufacturing Comparison 2026
| Business Type | Investment (₹) | Capacity | Net Margin | Export Potential | Difficulty |
| Water-Soluble NPK Plant | 50L – 2 Cr | 1–10 MT/day | 22–35% | High (Asia) | Medium |
| Nano Fertilizer Unit | 1.5 Cr – 5 Cr | 500L–2KL/day | 35–50% | High (SAARC) | High |
| Chelated Micronutrients | 75L – 3 Cr | 500 kg–3 MT/day | 30–45% | Medium | High |
| Humic/Fulvic Acid | 40L – 1.5 Cr | 1–5 MT/day | 25–40% | High (EU) | Low-Medium |
| Controlled-Release Fert. | 2 Cr – 8 Cr | 2–10 MT/day | 35–50% | Medium | Very High |
| Bio-Stimulant/Seaweed | 60L – 2.5 Cr | 500L–3KL/day | 28–42% | Very High (EU/US) | Medium |

Conclusion: The Window Is Open — But Not Forever
The Economic Times has handed India’s entrepreneurial community a rare early-warning signal. When the country’s largest fertilizer corporations pivot their entire strategy toward specialty products — investing billions in water-soluble fertilizers, nano formulations, and chelated micronutrients — they send a clear message to manufacturing startups: the demand infrastructure is being built right now.
The window of opportunity in specialty fertilizer manufacturing is open — but it will not remain open indefinitely. As major players complete their specialty product capacity buildout, they will inevitably turn their distribution and marketing muscle toward the same farmer segments that currently represent greenfield territory. The manufacturers who establish quality credentials, distributor networks, and farmer loyalty over the next 24 months will become trusted incumbents when that consolidation phase arrives.
India’s specialty fertilizer market is not a speculative bet. It is a structurally sound manufacturing opportunity backed by irreversible agricultural trends: horticulture expansion, precision irrigation, import substitution pressure, and subsidy rationalization. The Economic Times reporting on fertilizer giants’ specialty pivot simply confirms that this structural shift has reached institutional scale.
For entrepreneurs evaluating manufacturing sectors, specialty fertilizers offer something rare: a combination of government policy support, genuine import displacement potential, high margin profiles, and a domestic farmer base whose willingness to pay for quality inputs is demonstrably rising. This is an ET-validated, market-confirmed, founder-ready opportunity.
Act now. The first movers in India’s specialty fertilizer manufacturing sector will define the market for the next decade.